OMNIA Holdings said on Monday it had received a buyout offer from Indian company Solar Industries worth R21.5bn.
The offer, which values the South African mining explosives and agribusiness group at R134.50 per share, represents a 35% premium to its volume-weighted 30-day average share price. As such, Omnia management plans to recommend the buyout to shareholders.
The buyer, Solar Industries, is listed on India’s National Stock Exchange and operates in the explosives, defence and aerospace industries. It has a market value of about $21bn (R340bn).
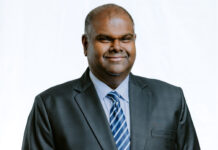
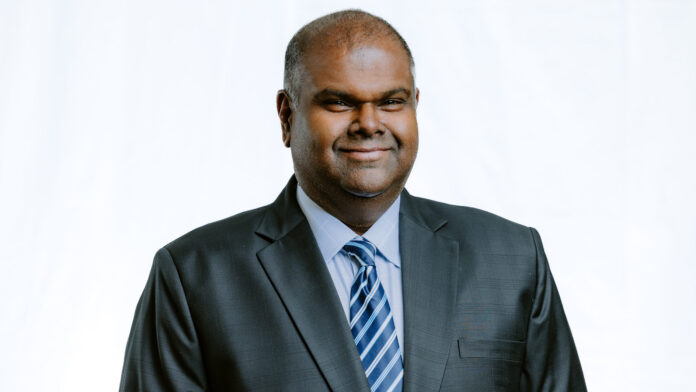
Seelan Gobalsamy said the proposed transaction supports Omnia’s offshore strategy. “This is an important milestone in Omnia’s 73-year history,” he said in a statement. The transaction would create “a powerful platform to accelerate BME’s ambition to become a global mining solutions business of scale”.
“Solar is the biggest explosives business in India, but BME is considerably further advanced across the rest of the world,” said Gobalsamy in an interview later on Monday. “So Solar would benefit from distributing some of its products through Omnia’s international network, and Omnia could, in turn, send some of its products into the Indian market,” he said.
Solar Industries also supported Omnia’s strategic intention to expand its agribusiness footprint in southern Africa. “They [Solar] want to expand into agriculture, and they see the Omnia agri asset as a very unique, well-established business,” he said.
The day-to-day running of the company will remain in the hands of current management. “Solar isn’t making an offer for all the shares because they want someone else to run it,” said Gobalsamy. “I think they’ve been clear in their engagement with us: it’s us, this management team.”
It is likely, however, that Omnia will be delisted from the JSE if the transaction is supported by shareholders. About a fifth of shareholders had already pledged support for Solar’s offer. A vote for the deal by 75% of attending shareholders would “win the day” for the offer, Omnia said.
Shares in Omnia surged 15% on Friday, reaching their highest level in five years, after Omnia published a cautionary announcement saying it was involved in a potential buyout discussion. At the close of trade on Monday, the share hit a new five-year high of R124.43/share, a 5% gain, valuing the company at R20.19bn.
Omnia declared a total dividend of 750c per share for its financial year ended March 31, which included a special dividend of 280c, returning R1.2bn to shareholders. This represents another strong performance, and a far cry from Omnia’s position in 2018, when debt had ballooned to about R4.8bn – more than the company’s entire market cap of R1.9bn at the time.
Since its turnaround in 2020, the group has returned R6.8bn to shareholders in dividends and share repurchases. Much of this recovery has been driven by Omnia’s mining explosives division, BME. At R1.4bn, BME accounted for 51% of Omnia’s total operating profit in its 2026 financial year, down from 66% of profit a year earlier.
Asked whether Omnia was running out of road in terms of its BME performance, Gobalsamy replied: “No, I don’t think we’re running out of road. If I go back two years, BME made the bigger contribution the year before; what happened last year is that agriculture just had a higher contribution.”
“I think the premium Solar is paying reflects the strong growth expected in the business,” said Gobalsamy. “They’re paying up to a higher share price than the spot price, which assumes we’ll deliver on our plans over the next two, three, four years, irrespective of conditions, and irrespective of mining production being a little down.
“Look through all of that, and it’s a fair value, with some of that future value being priced in up front.”